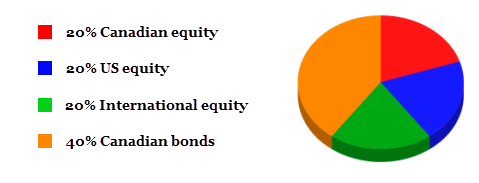5/22/2014

Overdraft

Continuing on in our My Money, My Choices journey - we come to overdraft.  I've thankfully never lived in it, but have in the past dipped into a few times by accident.  The cashflow exercise we went through a month or so ago really helped getting this straight so that we weren't having bills automatically debit from the account before pay day.

The great thing though, about banking with Tangerine is their Whoops! Protection...which is their version of overdraft protection.  Everyone, automatically gets 30-day protection to a maximum of $250 - FREE for 30 days.  So, if your account is accidentally withdrawn because of a miscalculation on the dates, you won't be charged for it or suffer a NSF fee.

Now, it is only free to a point.  You'll be charged $2.50 if it takes you longer to pay it back after the 30 days, and every 30 days after that if you fail to get your account balance back into the black.

Gail suggests that the easiest way to ensure you never dip into overdraft is by creating your own OD protection - something that Jordan and I have done for a long time.  Our's is about $1,000 - there's never less than that in the account.


5/21/2014

My Money, My Choices - Level 4, Activity 3 and 4

Activity 3 is one I can really sink my teeth into, in this one, we have to check our credit history reports.  Activity 4 is to correct any errors.  I requested them for both Jordan and I on April 14th from both Equifax and Transunion and the Equifax ones arrived last week.

Managing your credit is your responsibility, and checking in on the two bureaus is part of that job to make sure that everything is right....waiting until you need credit, until your buying a home, refinancing, getting a credit card - whatever - is NOT the time to do this...because repairing mistakes can take time to fix.

I'm very pleased to share that everything is in good order!  The Kia and the Amex show up on Jordan's report and the Escape, LOC, Joint C/C, Cell Phones and my Visa show up on my report.  The mortgage however; is missing.

I called them, and apparently they only report to TransUnion - so we'll wait another week or so until that report shows up and check.

They do have some wrong contact information for us, and they haven't updated Jordan's job - so we'll get that sorted out and check this off as complete.


5/20/2014

My Money, My Choices - Level 4, Activity 1 & 2

Level 4 is all about credit...which is a tool and important to learn how to use well.  When credit, turns to debt it becomes a tool that weighs us down and prevents us from achieving financial independence.

Activity 1 is to get a credit card...well that's an easy one to check of as complete.  I have a personal VISA in my name only that I use when travelling for work to keep those expenses separate and Jordan and I have a joint AMEX (with him as primary) and a joint Mastercard (with me as primary).  It's really important for our own credit identities to ensure that each of us is the primary on at least one; that way when the credit card companies report to the credit reporting agencies - we're both building a good credit history.

Activity 2 is to consistently use credit - I'm comfortable tracking that activity as complete as well because we use our cards and pay them off consistently.

5/16/2014

Coffee Addiction

I am addicted to coffee.

Not Starbucks lattes, or frappes or whatever - just awesome coffee.

So what's this picture all about?  Why am I camping in my kitchen?  Because my awesome Bunn Coffee maker died a week ago...DIED!

Okay, just the heating element crapped out.  But guess what - it had a three year warranty and was only 2.5 years old.  So we shipped it away, and the new one should be here early next week.

But in the meantime my frugal friends, I am making drip coffee using some of my camping gear rather than buying coffee at Tim Horton's every morning.

5/14/2014

I Went Shopping!

I don't generally shop for the enjoyment of it - especially clothes shopping...but it was getting a bit desperate in my closet, so I asked Jordan (who's much better at it than I am) to come with me.

I had some money from last Christmas and other personal savings for the trip.

Here's what I picked up:

  • 4 tops/blouses
  • 1 sweater
  • 2 capris
  • 1 pant
  • 1 skirt
  • 1 dress
  • 1 blazer
  • 1 spring jacket
I spent a grant total of $519.78...before coupons and discounts the original price tag would have been $265.27 higher.  Not bad for a Saturday afternoon!

5/13/2014

Investing - Asset Allocation

After writing about my pension asset mix a month or so ago, I felt like I hadn't really finished the exercise so I went to the front page of the internet and found a sub-reddit for personalfinancecanada and there I asked about pensions and asset allocation - and what I got, was a big lesson that I wanted to share with you.

First, if you haven't seen it before - I would really encourage you to check out the Canadian Couch Potato Blog.  It's written by Dan, and Dan's got a lot of credibility on the topic of investing in Canada.

no, this is not a sponsored post, I'm just excited about it.

On his site, and through some help on reddit - I learned a bit about index funds and some recommended approaches for setting an investment mix.   One of the approaches, which appealed to me had a balance of bond and index funds - for the medium risk appetite.

I totally see now, why those that commented on my last post about the topic thought my investments didn't have enough equity built into the mix.  Someone on reddit suggested I
  1. Determine your preferred asset allocation (ie, above graph)
  2. In a spreadsheet, pool all of the values of your various accounts and parcel the total out into buckets representing the percentages from #1 to the various asset classes.
  3. Distribute the individual asset class values across the accounts based on tax efficiency. You match asset classes and accounts. A spreadsheet is really helpful for this.
So, I did just that...and here's what my current state of affairs looks like including all investments.


Then, I played.

I played and looked at my investments until I came up with the following 'future' state...which is what I'm thinking of doing.  Basically, it involves:
  • Changing my TSFA DISA to the Tangerine Balanced Income Fund
  • Adding the balance of my RRSP DISA to my RRSP Tangerine/Streetwise Equity Growth
  • Adjusting the asset mix of my pension (tossing Trimark has it had high MER without higher growth)


I wanted to put this back out to you before I actually made the changes.  What do you think?  Am i missing something?  Do you think the advise to go with the Canadian Couch Potato Asset Allocation (40-20-20-20) is a good one, or do I still have too much in bonds?


5/12/2014

Debt Update

Just a quick update on where the debt stands.  All three credit cards have a $0 dollar balance, the Kia isn't tracked here because it's at 0% interest and the mortgage is...the mortgage.

As of Friday last week, the balance on the Escape and LOC was $34,900.  I've been continuing to add debt snowflakes to both accounts, but primarily to the Escape - because once it's paid, we can't add more to the pile (unlike the LOC), and it's interest rate is 1.5% higher than the LOC.

I've also included a bit of a breakdown of where the debt will stand at the end of the year with our regular payments.  My dream would be to have the balance at $0 but there's just no way we're going to find the money....My hope however, is that we're under $20K combined.

Once the balance is down another 5K, I'll pay off the Escape with the LOC, and we'll put the entire payment on to the single debt and then continue to decrease the available credit we have on the LOC until it's down to maybe $15K available.

Bit, by bit.

Links ♥

Followers